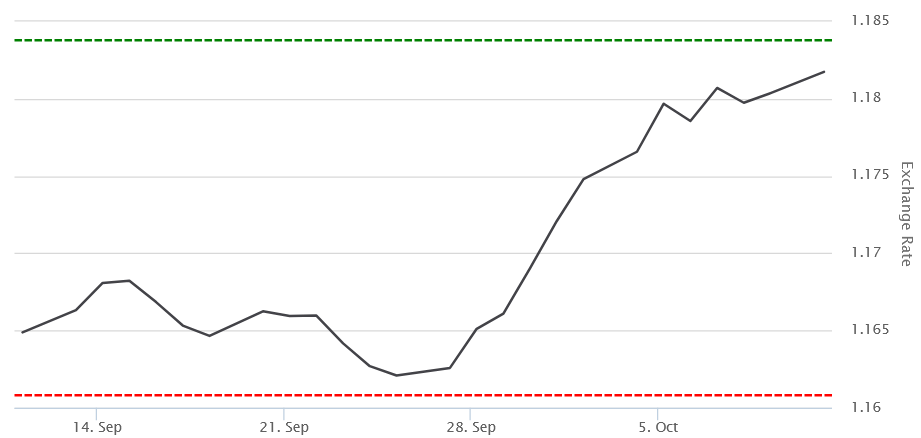
The euro remains firmly under pressure having recorded its second consecutive week of losses against the pound and the US dollar last time out. Sterling begins Monday slightly stronger against the US dollar but still around four cents down compared to the end of August.
This week’s focus may well fall on Ukraine given President Trump’s efforts to ease oil prices before next month’s midterm elections. Kyiv was blindsided over the weekend by a US proposal to halt strikes on energy infrastructure. The White House claimed both Ukraine and Russia had agreed to the terms, although President Zelenskyy appeared initially surprised by the news.
Despite the improvement in the energy picture in Ukraine, things in the Middle East took a negative turn after Houthi militants twice struck Riyadh airport. All this meant the brent crude index was little changed at around $103 this morning.
If you’d like to read more about how these dizzyingly complex goings-on could affect your business in the final months of this year, be sure to pick up your copy of our October-December Quarterly Forecast. In the report, you’ll find key charts, exchange rate predictions as well as analysis of all the biggest trends as we head towards the new year.
It will be a busy week for US markets once they return from the Columbus Day festivities today. Inflation data arrives across Wednesday and Thursday along with data from the retail and constructions sectors.
The International Monetary Fund and World Bank’s annual meetings also mean there will be heavier flow than usual of key policy figures doing the rounds at the conference circuit. The Bank of England’s Huw Pill and European Central Bank (ECB) president Christine Lagarde will both give remarks, as will several governors of the Federal Reserve.
There are suggestions that the UK’s impressive growth streak may have come to an end in August. Economists expect Thursday’s data to show a mild contraction in the economy, and the pound will be sensitive to any negative signals given the parlous state of government finances.
EUR: French finances restrict recovery
The euro was little changed against its peers this morning but remains at the centre of a debt storm. Concerns about France’s public finances are a significant drag, with French borrowing costs hovering around their highest in 25 years. This has also added to the ECB’s dilemma as expensive energy and weak confidence pull the economy in opposite directions.
USD: Inflation headlines dollar’s week
The US dollar eased fractionally in early trading but remains close to last week’s 18-month high against a basket of its rivals. Wednesday’s inflation figures will likely be the main test. Headline and underlying price growth are both expected to have accelerated, although markets still place roughly a four-in-five chance on the Federal Reserve leaving rates unchanged later this month.
Below you will find the current live exchange rates and movements in the currency markets. Please note that these rates are only accurate at the time of sending and should be used as an indication only.