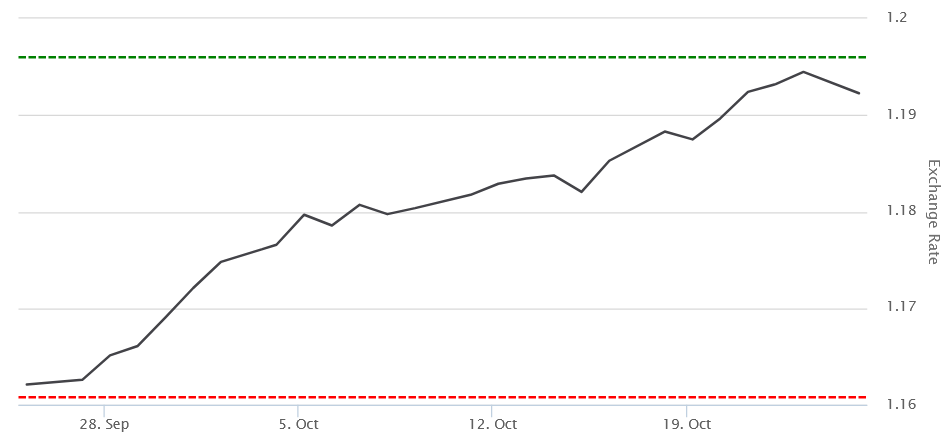
The pound must navigate Wednesday’s autumn Budget having strengthened to its best level against the euro since April 2025 to end last week.
Chancellor John Healey is ironing out the last details and media reports suggest this could be a low-key, ‘do no harm’ type of event. Politicians (and the public, it must be said) have the disastrous impact of past Budgets imprinted on their memories. However, sterling’s strong run of performances against its rivals could be under threat even if the chancellor opts for the restrained path.
In terms of what we might expect from the Budget, it’s fair to say the Treasury has little in the way of wiggle room. With energy prices eating into the government’s spending ambitions, most analysts are predicting a few modest cost-of-living measures, balanced on the revenue side by taxes on bank profits. Of course, we won’t know quite how this all shakes out until the Chancellor makes his address.
It looks set to be a busy week for Europe and America as well. The European Central Bank and the Federal Reserve will make their latest interest rate decisions within 24 hours of one another. The current consensus is that both will leave rates unchanged, but it’s tough to rule out another hike in both cases.
The back end of the week sees an unusually high volume of significant data points. GDP and inflation data arrives for the US and key eurozone economies across Thursday and Friday.
Financial markets were rocked last week by the double-whammy of high oil prices and a pullback in AI stocks. There may be some more bumps this week, with rumours of further US military activities in the Middle East and the latest earnings releases from tech giants Microsoft, Alphabet and Amazon.
The brent crude global benchmark bared down on its highest level since June 2022 to end last week. Prices have now risen for three consecutive weeks and the impact is wreaking havoc on government borrowing costs and inflation across the globe.
If that wasn’t enough, a series of huge elections kicked off over the weekend. Brazil’s incumbent president Lula won a shock victory over Flávio Bolsonaro, while the student-led movement looks set to record an equally stunning victory in Serbia. Voters will also go to the polls in Israel this week before the midterm elections in the US.
While Britain’s consumer confidence plunged in October, there were at least strong signals of activity from the country’s manufacturing and services sectors. Output in both segments came in well above forecasts, although that failed to provide a real boost for the pound ahead of Wednesday’s autumn Budget.
EUR: France rocked by more protests
70,000 police officers were deployed across France this weekend to quell the unrest that has ripped across the country in recent weeks. The strife has further exacerbated the strains in French government debt and made it difficult for the euro to make any real progress against its rivals.
USD: Focus shifts to Fed
Expectations about what the Federal Reserve has planned for the rest of 2026 have played a big part in the US dollar’s recent performance. A strong end to last week was mainly fuelled by predictions that the Fed would have to leave interest rates higher for longer than expected. We’ll see what Kevin Warsh has to say about that, although his move away from forward guidance has led to an increase in sharp movements based off seemingly throwaway comments.
Below you will find the current live exchange rates and movements in the currency markets. Please note that these rates are only accurate at the time of sending and should be used as an indication only.